How Much Car Can You Afford in Your 20s? The 20/4/10 Rule
Your first real car purchase is exciting, and it is also one of the easiest places to make an expensive mistake. A dealer will ask what monthly payment you want, stretch the loan to hit that number, and send you home in a car that costs far more than the sticker price suggests. In your 20s, when income is still growing and savings are thin, that can mean years of tight cash flow.
A simple guideline can keep you out of trouble: the 20/4/10 rule. This guide explains what it means, shows real numbers for different incomes, and walks through the costs people forget. You can test your own price, rate, and term with an auto loan calculator while you read.
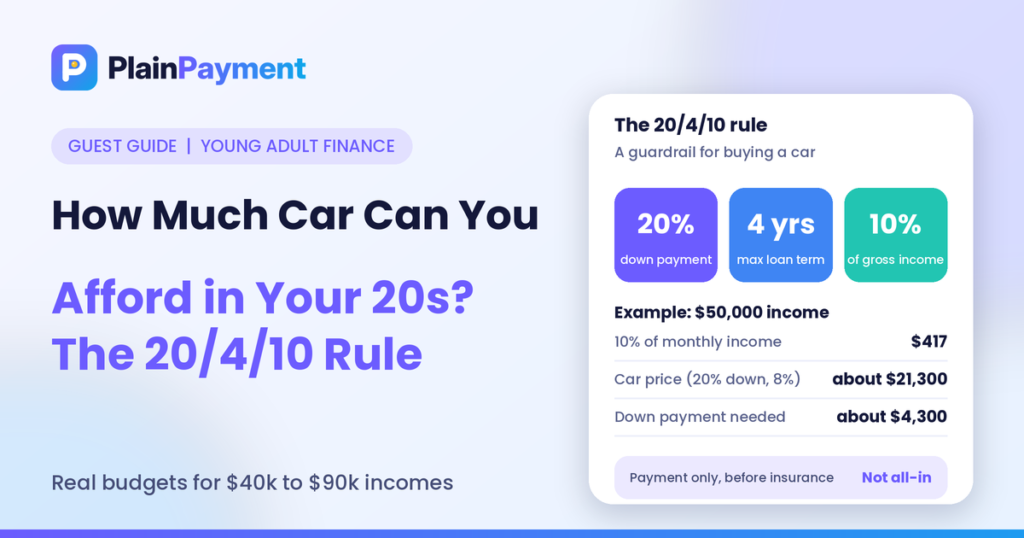
Quick Answer: What Is the 20/4/10 Rule?
The 20/4/10 rule says:
- 20: Put at least 20% down on the car.
- 4: Finance for no more than four years (48 months).
- 10: Keep your monthly car expenses to no more than 10% of your gross monthly income.
In the example below, someone earning $50,000 a year has about $417 a month to work with. If that covers only the loan payment, the rule supports a car of about $21,300, with about $4,300 down. If it covers the payment plus insurance, fuel, and maintenance, the budget shrinks to a much cheaper car. That difference is the most important thing to understand before you shop.
What Each Part of the Rule Does
20% down
A large down payment protects you from owing more than the car is worth. New cars lose value quickly, and a loan with little or nothing down can leave you with negative equity, meaning you owe more than the car would sell for. A 20% down payment also lowers the loan, the payment, and the interest.
4-year loan term
Shorter loans cost less in total interest and get you out of debt sooner. Longer loans lower the monthly payment, which is why dealers like them, but they raise the total cost and keep you paying while the car ages and needs repairs.
10% of income
This is the spending cap. It keeps car costs from crowding out rent, savings, and other goals. The strict version counts everything: payment, insurance, fuel, and maintenance. A looser version counts only the payment. We will show both.
The Example Used in This Guide
All numbers are illustrations, not offers. Your rate, insurance, and costs will differ.
- Loan: 48 months at 8% APR
- Down payment: 20% of the price
- Gross income: shown in each table
- Other monthly car costs in the strict version: $300 total, made up of $150 for insurance, $100 for fuel, and $50 for maintenance
- Taxes, registration, and dealer fees are not included
How Much Car Can You Afford at Different Incomes?
First, the payment-only version, where 10% of gross monthly income covers just the loan payment:
| Annual income | Monthly gross | 10% limit | Maximum car price | Down payment (20%) |
|---|---|---|---|---|
| $40,000 | $3,333 | $333 | about $17,070 | about $3,410 |
| $50,000 | $4,167 | $417 | about $21,330 | about $4,270 |
| $60,000 | $5,000 | $500 | about $25,600 | about $5,120 |
| $75,000 | $6,250 | $625 | about $32,000 | about $6,400 |
| $90,000 | $7,500 | $750 | about $38,400 | about $7,680 |
Now the all-in version, where 10% must cover the payment and $300 of insurance, fuel, and maintenance:
| Annual income | 10% limit | Left for the payment | Maximum car price |
|---|---|---|---|
| $40,000 | $333 | $33 | about $1,700 |
| $50,000 | $417 | $117 | about $5,975 |
| $60,000 | $500 | $200 | about $10,240 |
| $75,000 | $625 | $325 | about $16,640 |
| $90,000 | $750 | $450 | about $23,040 |
The all-in numbers look harsh, and that is the point. Owning a car costs far more than the loan payment. If your budget only supports an inexpensive car under the strict rule, you have learned something valuable before signing anything. Insurance for younger drivers can run higher than the example, which makes the strict version tighter still.
A Realistic Middle Ground
Many people use a blend. They aim for a payment near 10% of income, but they also check that total transportation costs stay in a reasonable range, often cited as around 10% to 15% of gross income. Here is how the $50,000 earner looks when they buy a car at the payment-only limit:
| Monthly cost | Amount |
|---|---|
| Loan payment (about $21,300 car, 20% down, 48 months at 8%) | $417 |
| Insurance | $150 |
| Fuel | $100 |
| Maintenance and repairs | $50 |
| Total | $717 |
| Share of $4,167 gross monthly income | about 17% |
At 17%, the total is well above 10%. This is why the payment-only version can mislead you. The loan payment looks reasonable, but the all-in cost does not. If you see a total above 15%, consider a cheaper car, a larger down payment, or both.
Why the 4-Year Limit Matters
The monthly payment looks better on a long loan, but the total cost is worse. Take a $28,000 car and compare three ways to finance it, all at 8% for simplicity:
| Option | Down payment | Loan | Monthly payment | Total interest |
|---|---|---|---|---|
| 20% down, 48 months | $5,600 | $22,400 | $546.85 | $3,849 |
| 10% down, 60 months | $2,800 | $25,200 | $510.97 | $5,458 |
| $0 down, 72 months | $0 | $28,000 | $490.93 | $7,347 |
The 72-month loan has the lowest payment, about $56 less than the 20/4 option. But it costs about $3,500 more in interest, and it leaves you owing the most when the car is depreciating. Longer loans also often carry higher interest rates than shorter ones, which would widen the gap further.
Choosing the lowest payment is not the same as choosing the lowest cost.
What the 20/4 Part Costs at Different Prices
Here is how the loan works at several car prices under 20% down and 48 months at 8%:
| Car price | Down payment | Loan | Monthly payment | Total interest |
|---|---|---|---|---|
| $15,000 | $3,000 | $12,000 | $293 | $2,062 |
| $20,000 | $4,000 | $16,000 | $391 | $2,749 |
| $25,000 | $5,000 | $20,000 | $488 | $3,436 |
| $30,000 | $6,000 | $24,000 | $586 | $4,124 |
Each extra $5,000 of car price adds about $98 to the monthly payment. That is a quick way to estimate how a more expensive trim or model affects your budget.
The Costs People Forget
The sticker price and the loan payment are only part of owning a car. Add these before you decide:
- Insurance. Rates for young drivers are often higher, and they vary by car, location, and driving record. Get quotes before you pick a car, because two similar cars can have very different premiums.
- Fuel. Check fuel economy and estimate your monthly miles.
- Maintenance and repairs. Older cars often need more repairs. Budget a monthly amount even when nothing is broken.
- Registration, taxes, and fees. These can add hundreds or thousands at purchase, depending on where you live.
- Depreciation. New cars lose value fastest in the first few years.
- Parking and tolls. In some cities, these are significant.
- Interest. The true cost of the loan, not just the payment.
An easy way to estimate the true monthly cost is to add the payment, insurance, fuel, and a maintenance budget. If the total feels tight, the car is probably too expensive.
New vs Used: What Works Better in Your 20s
| Factor | New car | Used car |
|---|---|---|
| Depreciation | Fastest in the first years | Slower, because much of it has already happened |
| Price | Higher | Lower |
| Warranty | Usually comes with a manufacturer warranty | Varies, and may be limited |
| Reliability | Fewer repairs early on | Depends on age and history |
| Loan interest | Sometimes lower promotional rates | Often slightly higher |
| Insurance | Often higher | Often lower |
For many people in their 20s, a well-maintained used car with a lower price is the easiest way to stay inside the 20/4/10 guideline. Always get a pre-purchase inspection and a vehicle history report before you buy a used car.
How Your Credit Affects the Loan
Your interest rate depends heavily on your credit. A small difference in rate can change the payment and the total cost. An APR calculator shows the true yearly cost of a loan, including fees, so you can compare offers fairly.
If your credit is thin or fair, these steps can help before you apply:
- Pay every bill on time.
- Keep card balances low relative to their limits. A credit utilization calculator can show where you stand.
- Check your credit reports for errors.
- Consider a cosigner only if both parties understand the risk, because a cosigner is responsible for the debt.
Get pre-approved by a bank or credit union before you visit a dealer. It gives you a rate to compare and a spending limit you set yourself.
How to Afford a Car in Your 20s: A Step-by-Step Plan
- Find your gross monthly income. Use pre-tax pay.
- Calculate 10%. That is your starting limit.
- Estimate non-payment costs. Get an insurance quote, and estimate fuel and maintenance.
- Decide whether to use the strict or flexible version. The strict version includes all costs. The flexible version includes only the payment, but you should still check the total.
- Work backward to a price. Use an auto loan calculator with a 48-month term and 20% down.
- Save the down payment. Plan for 20% plus taxes and fees if possible.
- Get pre-approved. Compare rates from a bank, a credit union, and the dealer.
- Negotiate the price, not the payment. Focus on the total price of the car.
- Refuse unnecessary add-ons. Extended warranties and extras can add to the loan.
- Keep a reserve. Do not spend your last dollar on the down payment.
Do Not Skip the Emergency Fund
A car comes with surprise costs, and so does life. If the down payment drains your savings, one repair bill can send you to a credit card. Keep an emergency fund in place before you buy. An emergency fund calculator can help you set a target. Even a starter fund of $1,000 to $2,000 is a good first goal.
What If You Cannot Meet the 20/4/10 Rule?
The rule is a guardrail, not a law. If you cannot reach it, adjust instead of ignoring it:
- Buy a cheaper car. Lowering the price is the strongest lever.
- Save longer. More time means a bigger down payment.
- Lower your insurance cost. Compare quotes, raise your deductible if you can afford it, and ask about discounts.
- Consider alternatives. Public transportation, carpooling, or keeping your current car for another year can free up cash.
- If you must stretch the term, keep it as short as possible and plan to pay extra when you can.
- Think about gap coverage. If your down payment is small, ask whether guaranteed asset protection makes sense, since you may owe more than the car is worth early on.
What You Could Do With the Money You Do Not Spend
The money you save by buying a more modest car can go elsewhere. Suppose you choose a car with a payment $150 lower than the most expensive one you could finance, and you save that amount each month. A compound interest calculator shows how steady monthly savings can grow over time. In your 20s, small differences in monthly spending can become large differences in savings by your 40s.
Common Mistakes to Avoid
- Shopping by monthly payment. Dealers can hit any payment by stretching the term.
- Ignoring insurance. Get quotes before you commit to a car.
- Putting nothing down. It raises the loan and the chance of owing more than the car is worth.
- Choosing a 72- or 84-month loan. The interest adds up, and the car may need major repairs before the loan ends.
- Rolling negative equity into a new loan. It grows the debt on your next car.
- Skipping the inspection on a used car. Hidden problems can cost thousands.
- Forgetting registration, taxes, and fees. These increase your cash need.
- Using the whole budget on the car. You still need money for rent, savings, and emergencies.
Quick Checklist
- Calculate 10% of your gross monthly income.
- Get insurance quotes for the cars you are considering.
- Choose a loan term of 48 months or less if you can.
- Plan for 20% down, plus taxes and fees.
- Get pre-approved before visiting the dealer.
- Compare total monthly cost, not just the payment.
- Inspect and check the history of any used car.
- Keep an emergency fund in place.
Bottom Line
The 20/4/10 rule gives you a simple way to test any car purchase: 20% down, no more than four years of financing, and costs near 10% of your income. In the example, a $50,000 earner could support a car near $21,300 if the 10% covers only the payment, but the all-in cost came to about 17% of income, which shows why the full picture matters.
Start with your income, check the true monthly cost, and choose a car you can afford without stretching. These examples are for education and are not financial advice. A licensed financial professional or a credit union counselor can help you review your own budget.
FAQs
What is the 20/4/10 rule for buying a car?
It is a guideline that suggests putting at least 20% down, financing for no more than four years, and keeping monthly car expenses to no more than 10% of your gross monthly income. It is meant to prevent overspending and keep the loan manageable.
Does the 10% include insurance and gas?
In the strict version, yes. The 10% covers the loan payment, insurance, fuel, and maintenance. In a looser version, it covers only the loan payment. If you use the looser version, check that your total transportation costs still fit your budget.
How much car can I afford on a $50,000 salary?
Under the payment-only version in this guide’s example, about $21,300 with 20% down and a 48-month loan at 8%. Under the strict all-in version, it is closer to $6,000 because insurance, fuel, and maintenance use most of the 10%. Your own numbers will vary.
Is a 72-month car loan a bad idea?
It is often more expensive. The monthly payment is lower, but total interest is higher, and you owe money for longer while the car loses value. In the $28,000 example, the 72-month loan cost about $3,500 more in interest than the 48-month loan with 20% down.
Should a young adult buy a new or used car?
Many people in their 20s do better with a used car, because it usually costs less and has already gone through the steepest depreciation. A new car comes with a warranty and fewer early repairs. Check insurance costs and the total monthly cost for both.
How much should I put down on a car?
Twenty percent is the common guideline. More down means a smaller loan, a lower payment, and less risk of owing more than the car is worth. If you cannot reach 20%, put down as much as you can and keep the term short.
Does my credit score matter for a car loan?
Yes. A higher score usually earns a lower interest rate, which lowers your payment and total cost. Check your credit before shopping, and compare offers from banks, credit unions, and dealers.
